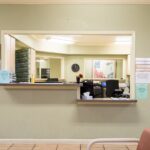
Several major banks are jointly piloting shared banking hubs in rural towns where individual branches have closed, giving customers of different banks one staffed place to deposit cash, withdraw money and discuss accounts face to face. The hubs, often based in refurbished shops or community buildings, provide counter services for all participating banks, with private rooms where staff from a specific bank attend on set days. Small businesses have been among the strongest supporters, because shops, cafes and market traders still handle significant cash and need secure local deposit facilities. Older customers also value help with forms and account queries that they find difficult to complete by phone or online. Organisers say sharing premises keeps costs manageable in places where no single bank could justify a full branch alone. The pilots include extended opening on market days in some towns and cash machines available outside staffed hours. Local councils have helped identify suitable buildings and promote the service, arguing that cash access supports the whole high street, since customers who travel elsewhere to bank often do their shopping there as well during the same trip each week.
What the Evidence Shows
Early usage figures suggest the hubs are busiest on market days and at the start of each month, when pensions and wages arrive. Business owners report spending less time travelling to distant branches, and several have returned to accepting cash confidently now that deposits are practical again. Customers interviewed praised being able to speak to a person, particularly when resolving bereavement paperwork, suspected fraud or power of attorney arrangements. Challenges include limited space at peak times and the need to explain clearly which services each day can offer, since specialist staff rotate between hubs. Digital volunteers run sessions in some locations, helping visitors who want to learn online banking while keeping the choice to use cash. Banking groups say decisions on permanent sites will follow the pilot evidence, including footfall, business deposits and customer satisfaction. Community groups are campaigning for hubs to be treated as essential infrastructure in towns above a certain size. Whatever the final model, the pilots have restarted a national conversation about how banking remains accessible as branches close and payments continue moving steadily online. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following shared rural banking hubs say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by shared rural banking hubs are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with shared rural banking hubs will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.